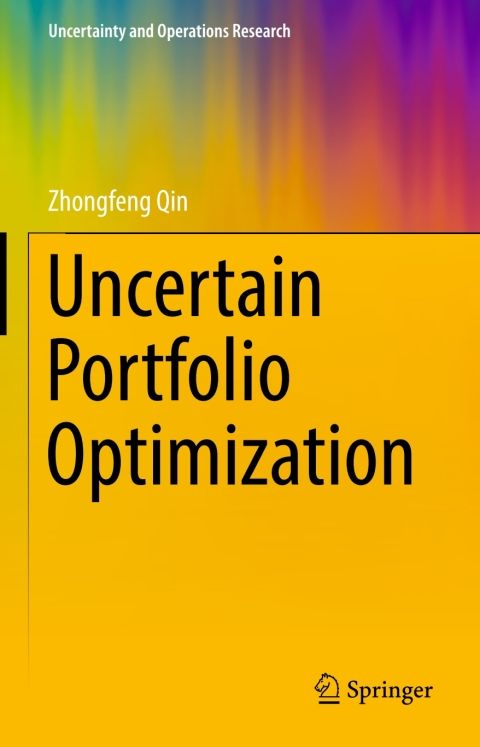
Uncertain Portfolio Optimization
Buy with confidence
✓ Digital eBook
✓ Dedicated customer support
✓ Refund if we cannot fulfill your order
This book provides a new modeling approach for portfolio optimization problems involving a lack of sufficient historical data. The content mainly reflects the author’s extensive work on uncertainty portfolio optimization in recent years. Considering security returns as different simples, the book presents a series of portfolio optimization models in the framework of credibility theory, uncertainty theory and chance theory, respectively. As such, it offers readers a comprehensive and up-to-date guide to uncertain portfolio optimization models.About this book
Book details
Related products