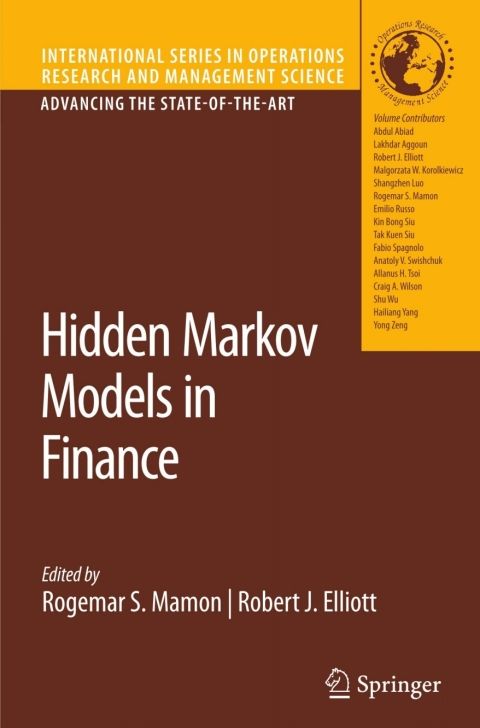
Hidden Markov Models in Finance

by Rogemar S. Mamon; ?Robert J Elliott | 1st Edition | Springer | eText ISBN 9780387711638
A number of methodologies have been employed to provide decision making solutions globalized markets. Hidden Markov Models in Finance offers the first systematic application of these methods to specialized financial problems: option pricing, credit risk modeling, volatility estimation and more. The book provides tools for sorting through turbulence, volatility, emotion,...

29.99 $
⚡
Digital eBook PDF / eTextbook
✉
Fast Delivery Instant – 48 hours
↓
Download Link Delivered via email
🔒
Secure Checkout Protected payment

Buy with confidence

✓ Digital eBook

✓ Dedicated customer support

✓ Refund if we cannot fulfill your order

About this book

A number of methodologies have been employed to provide decision making solutions globalized markets. Hidden Markov Models in Finance offers the first systematic application of these methods to specialized financial problems: option pricing, credit risk modeling, volatility estimation and more. The book provides tools for sorting through turbulence, volatility, emotion, chaotic events – the random “noise” of financial markets – to analyze core components.

Book details

  • Author: Rogemar S. Mamon; ?Robert J Elliott
  • Publisher: Springer
  • Edition: 1st Edition
  • eText ISBN: 9780387711638
  • Print ISBN: 9780387710815
  • Format: Fixed Layout
  • Language: en
  • Copyright: 2007